As expected, the Federal Reserve raised the overnight rate by 25bp (.25%). I think this was both the right move and irrelevant. Others disagree.
– The Fed cited high inflation, high spending, high employment, and solid economic growth.
– The dot plot shows 2 Governors who expect to keep the current fed funds rate through year end, 12 who expect to hike by an additional 25bp, and 4 who expect to hike by an additional 50bp by year end.
– Those who wanted the Fed to hold or cut are citing disinflation (that’s inflation but at a slower pace) and supply shocks from higher oil.
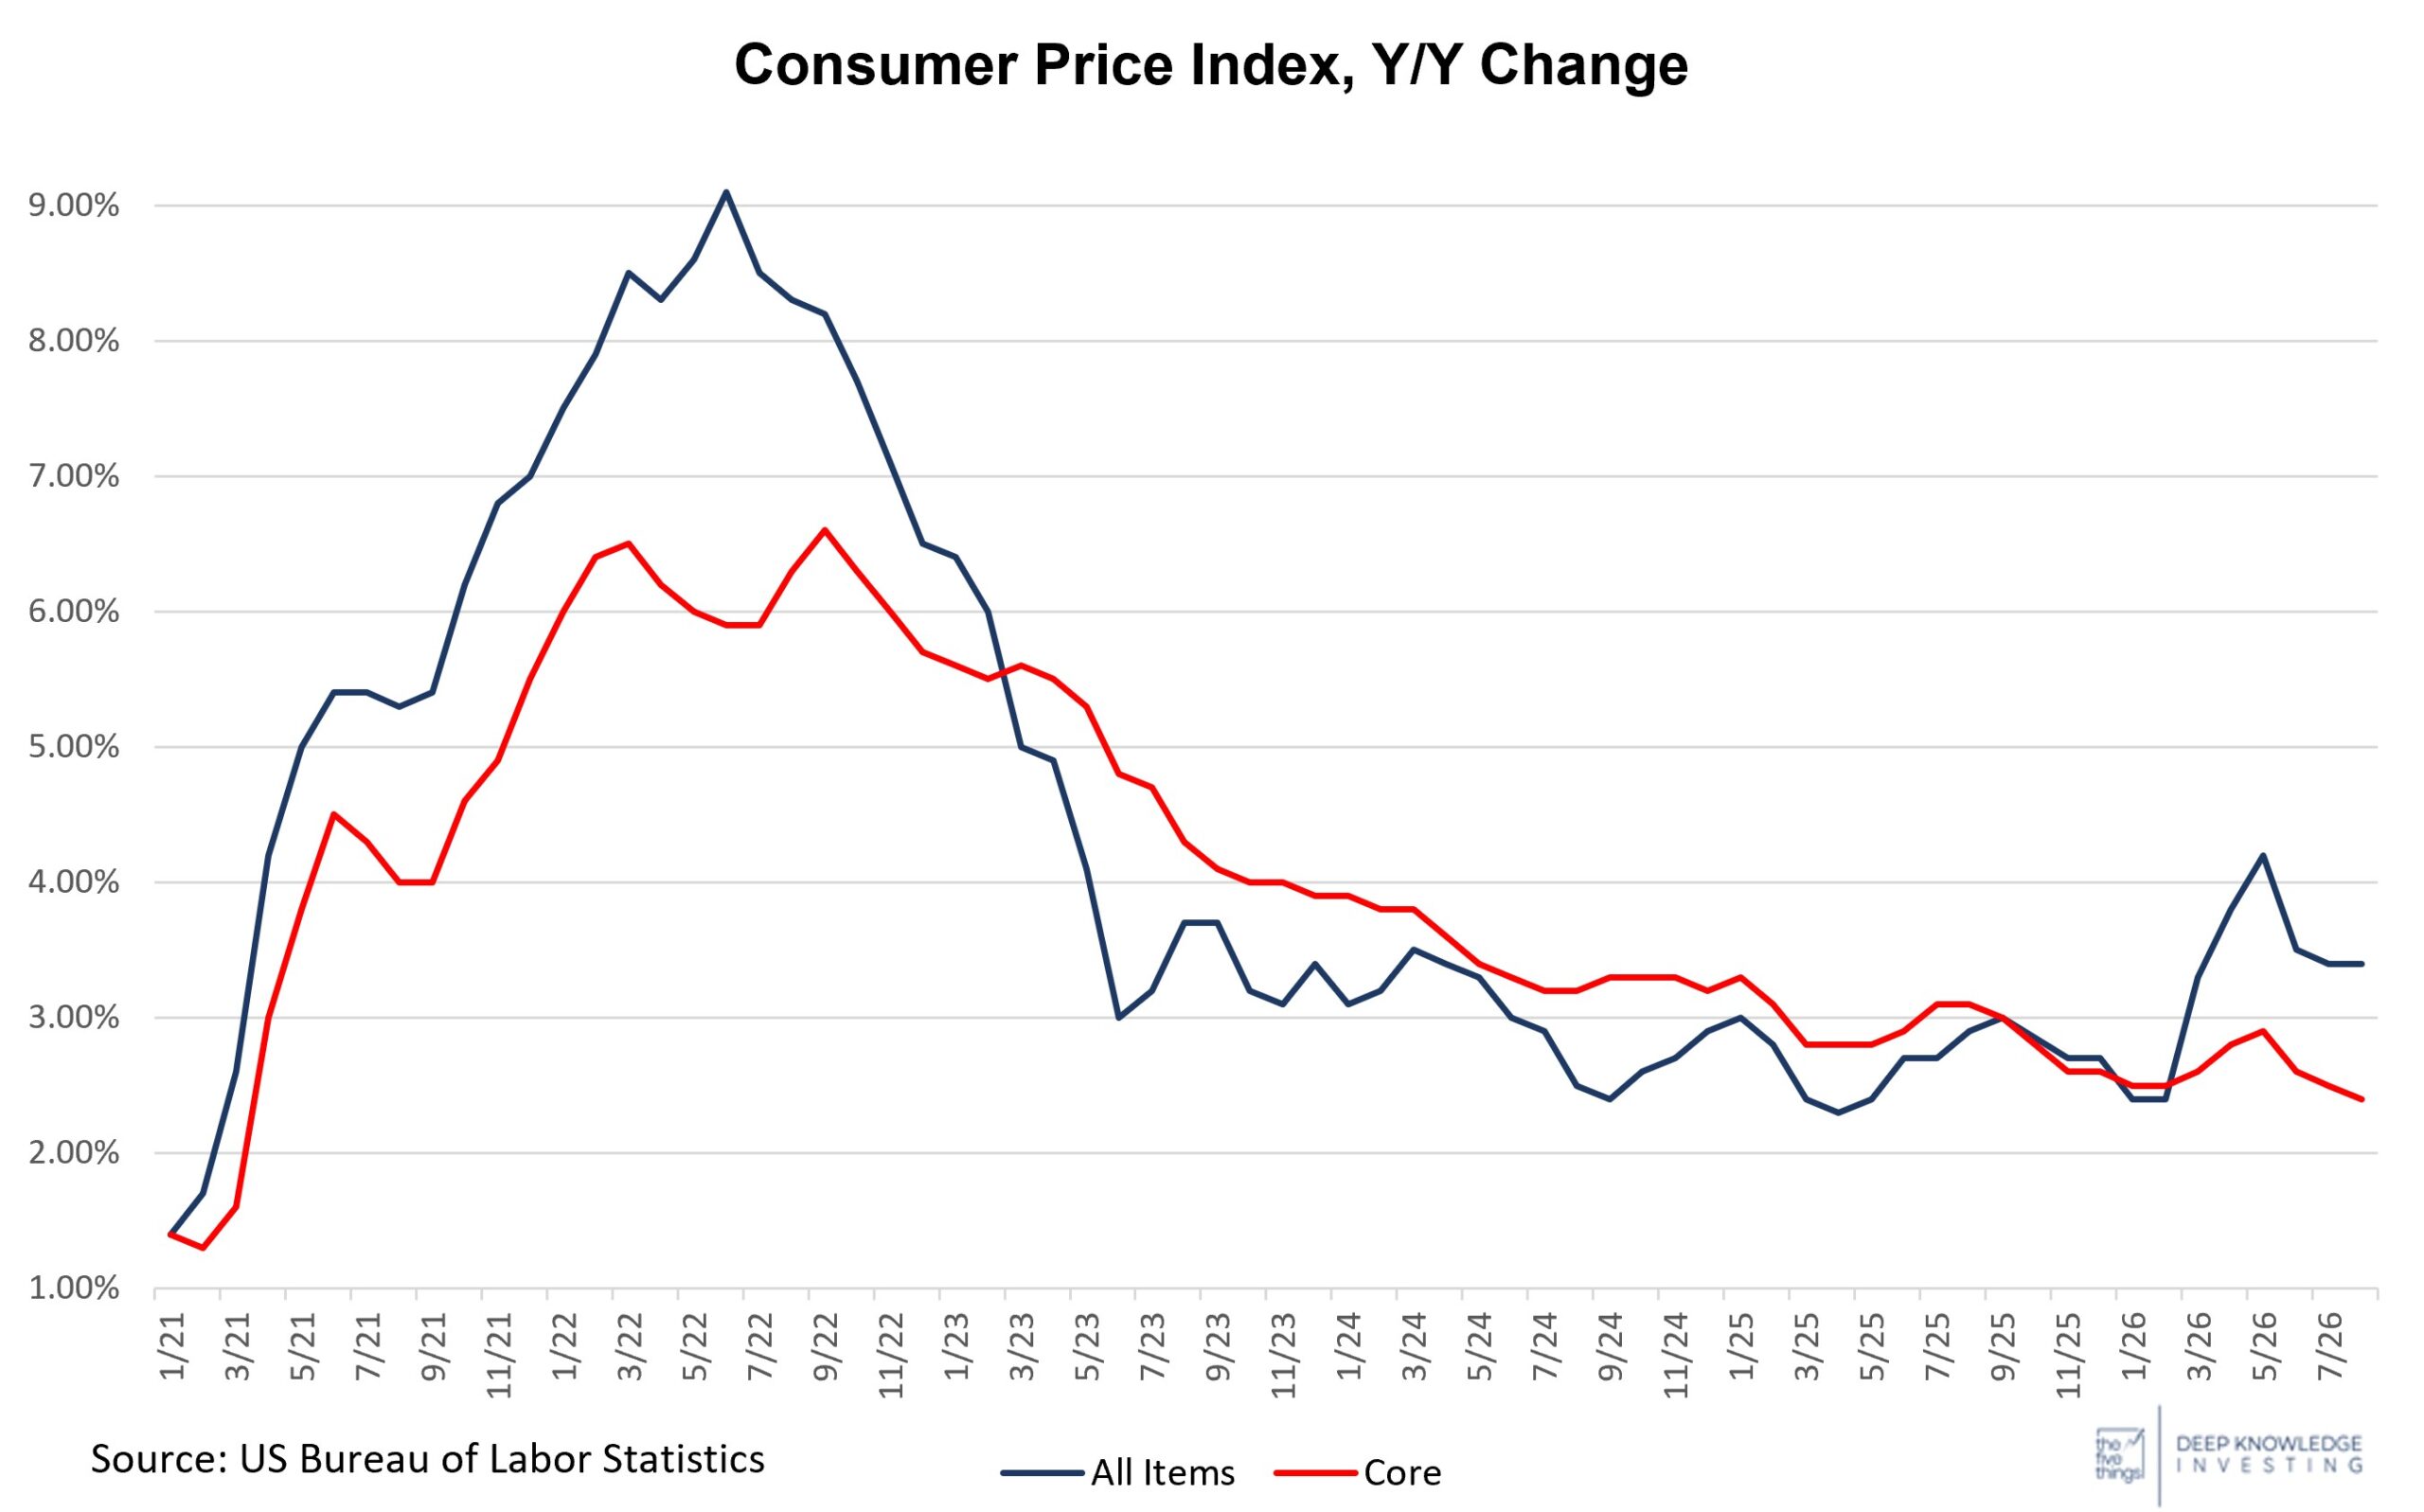
– I note that the Core CPI (all-items less food and energy) has been above the 2% target for more than half a decade. They don’t have inflation under control even backing out higher oil prices so if they’re not going to hike then they should admit the target is now 3% – 4%.
– I also don’t think it matters. Inflation (as experienced through higher prices) is continuing due to an expansion of the money supply (the true definition of inflation). That is happening because Congress overspends by trillions of dollars a year. We are funding guns (overseas military bases and wars), butter (a massive and ever-growing social safety network that incentivizes people not to work), the future (off balance sheet unrecognized liabilities for things like Social Security, Medicare, and pensions total over $200T), interest (Ponzi printing to pay for the interest on what we printed last year) and fraud (DOGE uncovered massive theft that no one in Washington DC wants to address). This is not sustainable and can’t be paid for by taxing billionaires. Like every fiat currency before it, expect continued loss of purchasing power due to inflation. Chairman Warsh, the Federal Reserve, and Secretary Bessent can’t change this.
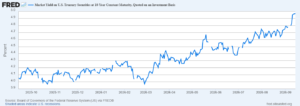
– The bond market sees this and is pricing in higher inflation regardless of what the Fed does with the fed funds rate which is only the overnight rate. We had roughly a year of cuts and a year of holding and this is what happened to the 10-year Treasury yield. For those who want the Fed to cut to get lower mortgage rates, I want to know how. The Fed can’t cut mortgage rates and the bond market knows this.
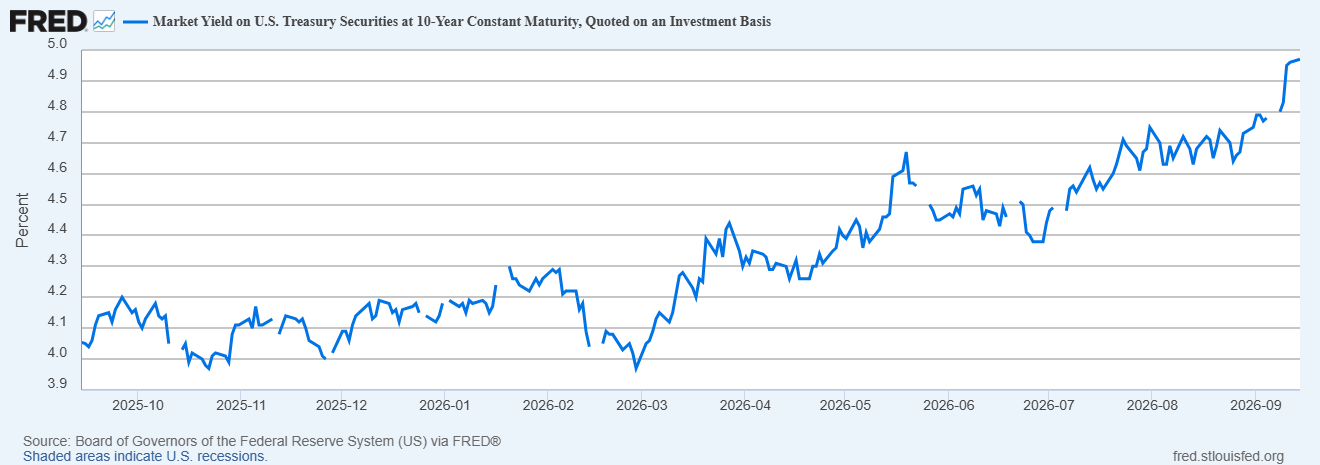
– The financial markets have been riveted by this Fed meeting because it’s sports for finance types. Ask yourself how your life and your portfolio will be changed by banks paying .25% – .50% more for overnight deposits at the Fed. Then, I would suggest investing based on what you think will happen over the next 2, 5, 10 years.
Information contained in this report is believed by Deep Knowledge Investing (“DKI”) to be accurate and/or derived from sources which it believes to be reliable; however, such information is presented without warranty of any kind, whether express or implied and DKI makes no representation as to the completeness, timeliness or accuracy of the information contained therein or with regard to the results to be obtained from its use. The provision of the information contained in the Services shall not be deemed to obligate DKI to provide updated or similar information in the future except to the extent it may be required to do so.
The information we provide is publicly available; our reports are neither an offer nor a solicitation to buy or sell securities. All expressions of opinion are precisely that and are subject to change. DKI, affiliates of DKI or its principal or others associated with DKI may have, take or sell positions in securities of companies about which we write.
Our opinions are not advice that investment in a company’s securities is suitable for any particular investor. Each investor should consult with and rely on his or its own investigation, due diligence and the recommendations of investment professionals whom the investor has engaged for that purpose.
In no event shall DKI be liable for any costs, liabilities, losses, expenses (including, but not limited to, attorneys’ fees), damages of any kind, including direct, indirect, punitive, incidental, special or consequential damages, or for any trading losses arising from or attributable to the use of this report.